JOE TOMKINS

Getting a mortgage can be stressful and confusing; it doesn't have to be, let me show you how. 
CALL ME LET'S TALK

JOE TOMKINS

Mortgage Broker 

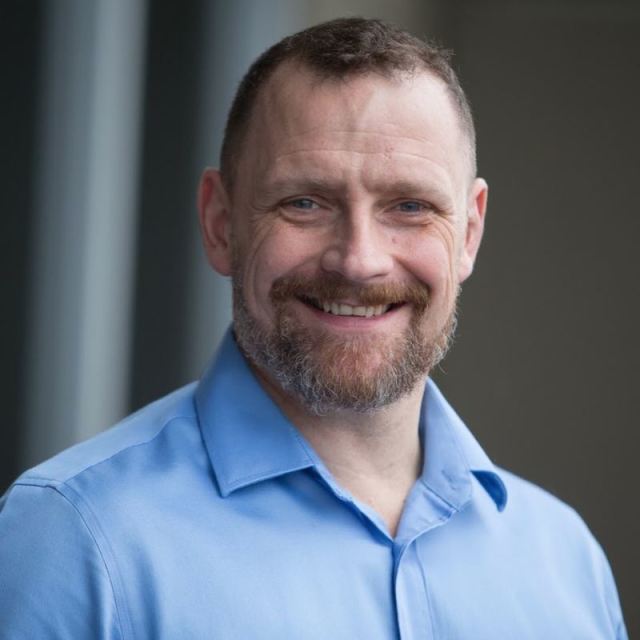
Hi, I’m Joe, and I have been actively involved in the mortgage industry since August 2003 and have a great deal of experience preparing mortgages, dealing with lenders and negotiating all aspects of mortgage underwriting. What can I say, I love what I do!


I value relationships and believe that my job is to firstly take care of my clients, making sure they understand the mortgage process, and then arrange a mortgage with a lending institution who is offering the product that best suits their needs. I believe in standing up for what matters in life and have no problems fighting to make sure my clients get the best mortgage possible.


Although I am proud of my many accomplishments in business, my real passion lies in spending time with my family. I have four healthy and beautiful boys who fill my spare time with constant fun and games. Neither my life nor my business would be as successful without my most important partner, my wife Nicole.

CALCULATE

Whether you're just getting started, have a home in mind, or want to refinance or renew an existing mortgage, why not start by using my online calculator? 
CALCULATE

SIGN CONSENT

We take your privacy very seriously. Here is a quick consent form that you can use to indicate that you'd like to start the process in finding a mortgage with me! 

SIGN CONSENT

APPLY NOW

You've run some preliminary calculations, you've signed the consent form, the next step is to go through my online mortgage application.  
APPLY

The Collective Mortgage Group provides mortgage services to loyal clients in a transparent environment, with an authentic voice, helping them feel protected, and save time and money.

LET'S TALK

Mortgage Financing


Whatever your mortgage needs; at The Collective Mortgage Group, we have the products you're looking for. Contact us anytime to find out more! 

First Time Home Buyers

If you're looking to buy your first home, we've got the advice (and expertise) you're looking for. Let our team of professionals guide you through the home buying process. 

Going Through a Divorce?

We get it, sometimes life happens. If you're going through a divorce, or separation, there are programs that might allow you to keep the matrimonial home. Make sure to contact us for more information!

Experienced Home Buyers

If you're looking to climb the property ladder, refinance, or renew your existing mortgage, let us help you arrange financing so you can get the best mortgage for you! 

Mortgage into Retirement

Older Canadians are looking for options. Although a great product for some people, the reverse mortgage isn't your only option into retirement. Let's discuss ALL your options, instead of making assumptions. 

The power of working with The Mortgage Collective is that you don’t just get a mortgage broker, you get the care and attention of our entire experienced mortgage team. 

LET'S TALK

YOU HAVE ACCESS TO ALL THE LENDERS

As a collective, we've developed excellent relationships with lenders across Canada. Let's figure out which one has the best product for you. 
Buying my home was a daunting task and I didn’t know where to start. I spent a lot of time researching but found it overwhelming. Joe took me through the process step by step, explaining everything until I was confident to make my decision. He worked very hard and was committed to doing everything he could to get me the home I had my heart set on.


I am so happy with the experience I had with Joe and would highly recommend him!

Sandra C.


MORTGAGE ARTICLES
Looking for a little more information before getting in touch? No problems! Have a look through my mortgage blog where I share valuable information about mortgage financing and the home buying process. Once you're ready, feel free to connect with me in whatever way you feel comfortable. 
By Joe Tomkins • November 19, 2026
For most Canadians, buying a home isn’t possible without a mortgage. And while getting a mortgage may seem straightforward—borrow money, buy a home, pay it back—it’s the details that make the difference. Understanding how mortgages work (and what to watch out for) is key to keeping your borrowing costs as low as possible. The Basics: How a Mortgage Works A mortgage is a loan secured against your property. You agree to pay it back over an amortization period (often 25 years), divided into shorter terms (ranging from 6 months to 10 years). Each term comes with its own interest rate and rules. While the interest rate is important, it’s not the only thing that determines the true cost of your mortgage. Features, penalties, and flexibility all play a role—and sometimes a slightly higher rate can save you thousands in the long run. Key Questions to Ask Before Choosing a Mortgage How long will you stay in the property? Your timeframe helps determine the right term length and product. Do you need flexibility to move? If a work transfer or lifestyle change is possible, portability may be important. What are the penalties for breaking the mortgage early? This is one of the biggest factors in the real cost of borrowing. A low rate won’t save you if breaking costs you tens of thousands. How are penalties calculated? Some lenders use more borrower-friendly formulas than others. It’s not easy to calculate yourself—get professional help. Can you make extra payments? Prepayment privileges allow you to pay off your mortgage faster, potentially saving years of interest. How is the mortgage registered on title? Some registrations (like collateral charges) can limit your ability to switch lenders at renewal without extra costs. Which type of mortgage fits best? Fixed, variable, HELOCs, or even reverse mortgages each have their place depending on your financial and life situation. What’s your down payment? A larger down payment could reduce or eliminate mortgage insurance premiums, saving thousands upfront. Why the Lowest Rate Isn’t Always the Best Choice It’s tempting to chase the lowest rate, but mortgages with rock-bottom pricing often come with restrictive terms. For example, saving 0.10% on your rate may put a few extra dollars in your pocket each month, but if the mortgage has harsh penalties, you could end up paying thousands more if you break it early. The goal isn’t just the lowest rate—it’s the lowest overall cost of borrowing . That’s why it’s so important to look beyond the headline number and consider the whole picture. The Bottom Line Mortgage financing in Canada is about more than rate shopping. It’s about aligning your mortgage with your financial goals, lifestyle, and future plans. The best way to do that is to work with an independent mortgage professional who can walk you through the fine print and help you secure the product that truly keeps your costs low. If you’d like to explore your options—or review your current mortgage to see if it’s really working in your favour—let’s connect. I’d be happy to help.
By Joe Tomkins • November 5, 2026
Co-Signing a Mortgage in Canada: Pros, Cons & What to Expect Thinking about co-signing a mortgage? On the surface, it might seem like a simple way to help someone you care about achieve homeownership. But before you sign on the dotted line, it’s important to understand exactly what co-signing means—for them and for you. You’re Fully Responsible When you co-sign, your name is on the mortgage—and that makes you just as responsible as the primary borrower. If payments are missed, the lender won’t only go after them; they’ll come after you too. Missed payments or default can damage your credit score and put your financial health at risk. That’s why trust is key. If you’re going to co-sign, make sure you have a clear picture of the borrower’s ability to manage payments—and consider monitoring the account to protect yourself. You’re Committed Until They Can Stand Alone Co-signing isn’t temporary by default. Even once the initial mortgage term ends, you won’t automatically be removed. The borrower has to re-qualify on their own, and only then can your name be taken off. If they don’t qualify, you stay on the mortgage for another term. Before agreeing, talk openly about expectations: How long might you be on the mortgage? What’s the plan for eventually removing you? Having these conversations upfront prevents surprises later. It Affects Your Own Borrowing Power When lenders calculate your debt service ratios, the co-signed mortgage counts as your debt—even if you never make a payment on it. This could reduce how much you’re able to borrow in the future, whether it’s for your own home, an investment property, or even refinancing. If you see another mortgage in your future, you’ll want to consider how co-signing could limit your options. The Upside: Helping Someone Get Ahead On the positive side, co-signing can be life-changing for the borrower. You could be helping a family member or friend buy their first home, start building equity, or take an important step forward financially. If handled with clear expectations and trust, it can be a meaningful way to support someone you care about. The Bottom Line Co-signing a mortgage comes with both risks and rewards. It’s not a decision to take lightly, but with careful planning, transparency, and professional advice, it can be done responsibly. If you’re considering co-signing—or want to explore safer alternatives—let’s connect. I’d be happy to walk you through what to expect and help you decide if it’s the right move for you.
By Joe Tomkins • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.

Leave a Message

Contact Us